
When an individual experiences police misconduct, the impact extends far beyond that person. Police officers hold significant authority, empowered by legislation to arrest, search, detain, and enter private property. However, when these powers are abused whether through unlawful arrest, unlawful stop and search, excessive force, or illegal entry the trust of the legal system relies on affected individuals coming forward. 2024/ 25 saw an all time high in the number of complaints logged against the police at 94,940. Of those, 32,172 complaints were formally recorded under statutory legal frameworks to be investigated or formally resolved.
Reporting misconduct and pursuing action against the police is vital not only for the victim’s justice, but for safeguarding public trust and ensuring the legal system’s accountability.
Holding Power Accountable – The How
When police officers act unlawfully, their misconduct should not go unreported. Without formal checks or legal action, officers who abuse their position face no consequences and are more likely to continue acting in this manner, putting the community at risk. A harrowing example of complaints not acted on is in the case of the then Police Officer Wayne Couzens who despite complaints lodged, went on to falsely arrest, rape and murder Sarah Everard in 2021.
People who feel mistreated have two primary avenues to pursue accountability:
Formal Complaints of misconduct : Submitted directly to the force’s Professional Standards Department (PSD), complaints trigger internal investigations into officer behavior. If upheld, sanctions range from managerial guidance to dismissal. While complaints address individual discipline, they do not result in financial compensation for the victim. The PSD is overseen by the Independent Office of the Police
Civil Claims for Compensation: A civil action allows individuals to claim damages against the police force itself for civil wrongs such as unlawful arrest, false imprisonment, assault and battery, malicious prosecution, misfeasance in public office, breaches of the Data Protection Act the Human Rights Act, the Equality Act & the Race Relations Act
Taking these routes forces the police force to examine internal procedures, disclose critical operational documents, and formally answer for the unlawful actions of its officers.
Breaking the cycle of police misconduct – The Why
Police misconduct can affect anyone regardless of age, sex, race, religion but some groups such as young males are systematically targeted for actions such as stop and search. By raising awareness of wrongful acts by Police officers, individuals are exposing unlawful actions, misconduct and patterns of bad practice that must be addressed. Raising this by making a complaint or pursuing a civil action, the person is highlighting a problem in the force that should be addressed for the sake of the community and protecting them from authoritative harm.
Things to consider when taking legal action against the Police
Understanding the legal process is essential when dealing with complaints against the Police. The below are some key points to understand:
Procedural Sequence: A civil claim cannot commence while criminal proceedings against the individual are ongoing. So if you are under investigation or have been charged with an offence by the Police you cannot start a claim against the police.
Complaint vs. Civil Claim: While a formal complaint can be filed alongside or prior to legal proceedings, a person is not required to make a complaint in order to bring a civil claim. Solicitors operating under Conditional Fee Agreements generally do not handle complaints directly, clients are often advised to manage complaints independently or focus their efforts on the civil claim.
The most common claims: The most frequent civil actions involve unlawful arrest, false imprisonment, unlawful stop and search and trespass to property.
Taking action against the police requires courage, but it remains one of the most effective tools for exposing unlawful actions of Police officers, securing fair compensation, and upholding the rule of law.
Author: Mark Reynolds
What happens when a serious injury affects your ability to return to work
Returning to work after a serious injury depends on your recovery, the demands of your role and whether your employer can make suitable adjustments. Some people return gradually, perhaps with shorter hours or lighter duties. Others cannot safely resume their previous occupation, even after rehabilitation. Both outcomes matter when assessing a personal injury claim. Your ability to earn a living after the accident can have a greater financial impact than the award for pain, suffering and loss of amenity, especially when the injury ends a career early.
What a return to work usually looks like
If you’re off sick for more than seven consecutive calendar days, you’ll generally need a fit note, formally called a Statement of Fitness for Work. You can self-certify for the first seven days. Since July 2022, registered nurses, occupational therapists, pharmacists and physiotherapists, as well as doctors, have been authorised to issue fit notes where appropriate. The note may state that you’re unfit for work or that you may be fit with support, such as a phased return, altered hours, amended duties or workplace adaptations. Occupational health advice can help. Agree review dates, pay arrangements and what happens if the adjustments stop working.
A fit note gives medical advice rather than automatically changing your contract. Your employer should discuss any recommendations with you and consider appropriate adjustments, although not every suggestion will necessarily be practicable. If suitable changes cannot be agreed, you may be treated as unfit for work for the relevant period. GOV.UK’s guidance on sick leave explains the process, including longer absences and sick pay.
When your employer has to make reasonable adjustments
An injury may qualify as a disability under the Equality Act 2010 if it has a substantial and long-term adverse effect on normal day-to-day activities. Long-term generally means lasting, or likely to last, at least 12 months. Amputations, spinal injuries and lasting neurological damage can meet that definition, depending on their effects. The effects matter more than the diagnosis.
Where the legal test is met, employers must make reasonable adjustments to address disadvantages faced by disabled workers. Examples include specialist equipment, accessible workstations, amended tasks, flexible hours, additional breaks or suitable alternative vacancies. Reasonableness depends on factors such as effectiveness, practicality, cost and available resources. The duty generally arises when the employer knows, or could reasonably be expected to know, about the disability and disadvantage. Record your requests and consider occupational health advice. A refusal to make reasonable adjustments can amount to disability discrimination, regardless of intent.
When returning to your old job isn’t possible
Some injuries prevent a return to physically demanding work despite rehabilitation and reasonable adjustments. Alternatives may include redeployment, retraining for less demanding work or different hours. Ill-health retirement may be an option under a particular pension scheme, but it isn’t automatic and the financial implications need careful review. Medical and vocational evidence can establish realistic options.
You should not feel compelled to resign without advice. Dismissal or pressure to leave following an accident may raise employment-law issues, including unfair dismissal or discrimination. Our guide on whether you can be sacked after an accident at work explains those concerns, which can arise separately from your personal injury claim.
How this affects your compensation claim
Loss of earnings can be a substantial part of a serious injury settlement. Compensation may address pay already lost while you recovered and reduced income over your remaining working life. In a long-term claim, those financial losses may exceed damages for the injury itself, depending on medical and financial evidence. Pension and retraining costs may also matter.
You are expected to take reasonable steps to limit avoidable losses, but that does not mean accepting unsafe work or returning before you’re medically able. A suitable phased return, adjusted role or retraining may be relevant. Compensation is assessed on what you could reasonably earn with your injuries, not on an assumption that everyone can resume their previous employment. These examples illustrate the calculation.
| Your situation | What it typically means for your claim |
|---|---|
| Full recovery, same job and pay | Past net earnings lost during recovery, alongside damages for pain, suffering and loss of amenity |
| Return to the same job and pay, but at a disadvantage if you ever lost it | Possible compensation for a proven disadvantage on the open labour market, sometimes called a Smith v Manchester award |
| Return to work, but in a lower paid or lesser role | Past losses and a potential future earnings claim for the difference, where supported by evidence |
| Unable to return to work at all | Past and potentially substantial future lost earnings and pension contributions, assessed against realistic working life and alternatives |
Other losses may matter too. In suitable cases, someone who loses particularly fulfilling work may seek compensation for loss of congenial employment, although this is not an automatic award for changing jobs. A weakened position in the labour market must also be supported by evidence, rather than presumed from a diagnosis. Before accepting a settlement, read why accident victims shouldn’t accept an offer before speaking to a lawyer. Settlements are generally final, making an early valuation risky. Keep evidence of your lost earnings, including payslips, tax records, pension information, contracts and correspondence about your return. Expert evidence may help assess future earnings.
Protecting a larger settlement
If you receive substantial compensation and claim means-tested benefits, ask how the payment will be treated. Personal injury compensation is normally disregarded for Universal Credit during the first 12 months after receipt. After that, money held personally may affect entitlement. A properly established personal injury trust can preserve the relevant capital disregard, subject to benefit rules and correct administration. Discuss the arrangements before settlement funds are paid, particularly if you receive benefits. Different means-tested benefits have their own rules, so check your individual circumstances carefully before payment.
Time limits and funding
In England and Wales, most adult personal injury claims must be issued in court within three years of the accident or the later date of knowledge, subject to exceptions. Children and people lacking capacity can have different limits. Under our no win no fee basis, if your claim isn’t successful, you won’t pay us anything. If it is successful, our fee is 20% plus VAT (24% in total), taken from the compensation you receive for your pain and suffering and for financial losses up to settlement. We never take a fee from compensation for future losses, such as future care or loss of earnings, and nothing else is deducted from your compensation. We’ll confirm all of this in writing before your claim starts. Our guide to how the personal injury claim process works explains the stages.
Frequently asked questions
Common questions about work following a serious injury.
Do I have to go back to work if my employer offers me a role I don’t think I can do?
You don’t have to accept duties that are genuinely unsafe or unsuitable for your medical condition. Discuss the role, fit note and occupational health advice with your employer. Refusing suitable work without good reason may affect compensation; seek advice.
Can I still claim compensation if I’ve gone back to work on the same pay?
Yes. You may still claim damages for the injury and past losses. If your lasting condition creates a genuine disadvantage when seeking other employment, an additional award may be considered even though your current salary is unchanged.
What if I’m self-employed?
You may claim lost earnings or profit where supported by evidence. Tax returns, accounts, invoices and business records can establish the effect of the injury. Document lost business opportunities too.
Will claiming compensation affect my benefits?
It can affect means-tested benefits after the applicable temporary disregard. For Universal Credit, personal injury compensation is normally disregarded for 12 months; a properly administered personal injury trust may protect it afterwards. Get individual advice before receiving payment.
How is future loss of earnings actually calculated?
The calculation depends on your age, pre-injury earnings, likely retirement, medical prognosis and realistic future work. Solicitors may use Ogden actuarial tables and expert evidence.
Talk to Mark Reynolds Solicitors
A serious injury may change when, how or whether you can work again, and the financial consequences deserve careful attention alongside rehabilitation. Mark Reynolds Solicitors can assess lost earnings, future employment prospects and the evidence needed before settlement. We offer no win, no fee funding on the terms explained above. Contact our team for a free, no-obligation conversation. We have offices in Liverpool, Runcorn and Warrington and can assist clients across England and Wales.
How home adaptations are valued after a life-changing injury
Home adaptations after a serious injury can range from installing grab rails and ramps to moving into a different, fully accessible property. Reasonable housing costs can form part of a personal injury claim. But valuing a more expensive home differs from ordinary adaptations, particularly after a Court of Appeal decision in 2020. That distinction matters for long-term planning.
What a home adaptations claim can cover
Smaller adaptations may include a ramp, grab rails, a stairlift or wider doorways. After a spinal injury or amputation, you might need a level-access bathroom, ground-floor bedroom, hoists, accessible kitchens or enough space for a wheelchair and carers. An extension or major alteration may be necessary. Following a severe brain injury, layout, supervision and safety requirements may be particularly important. Sometimes the existing house cannot reasonably be adapted, and a move to a more suitable property is the practical solution.
These expenses are generally considered special damages, the financial losses and expenses arising from an injury, rather than general damages for pain and suffering. Evidence of medical necessity, reasonable costs and future needs determines what can be recovered. Buying another property introduces a separate valuation problem because the home itself retains value.
Why the law doesn’t simply pay for a new house outright
Suppose your injury means you need a suitable home costing £200,000 more than you would otherwise have spent. It might seem that your compensation should automatically include the entire additional £200,000. The law considers another factor: the enduring value of the property.
A house is an asset that normally remains part of your estate. Unlike money used to pay carers or replace wages, its entire purchase price is not consumed through use. Awarding the whole additional capital sum could leave an asset worth more than the home you would have owned without the injury. The courts have therefore tried to compensate the extra housing need while avoiding an unintended financial windfall to your estate. That balance is difficult, particularly when suitable accommodation is essential to your independence and the money must be available when you need to buy.
How courts value additional accommodation costs today
For many years, the courts used the approach developed in Roberts v Johnstone in 1989. This calculated a notional annual investment return on the additional capital needed for housing, then valued that income stream over the injured person’s remaining life. It depended on the personal injury discount rate applicable at the time.
The approach became unworkable after the discount rate fell below zero in 2017. Applying a negative rate could produce no award under Roberts v Johnstone, even where a claimant had an established need for significantly more expensive accommodation. This created a serious problem: injured people could be forced to divert compensation intended for care, lost earnings or other essential expenses towards buying a suitable home.
In 2020, the Court of Appeal addressed this in Swift v Carpenter. Mrs Swift needed a property costing £900,000 more than the home she would otherwise have occupied, but the previous calculation had produced no accommodation award. The court instead calculated the additional capital cost and deducted the present value of the reversionary interest, reflecting the eventual value retained by the estate. It used an annual 5% rate to value that interest over a life expectancy of 45.43 years. This is the general approach for suitable cases, although the court recognised that different circumstances, including a short life expectancy, may require further consideration.
| Step | Swift v Carpenter example |
|---|---|
| Additional capital cost of suitable property | £900,000 |
| Value of the reversionary interest (5% rate over a 45.43 year life expectancy) | £98,087 |
| Accommodation award | £801,913 |
The 5% valuation assumption in Swift v Carpenter is different from the statutory personal injury discount rate used to calculate lump-sum compensation for other future losses, including care and earnings. In England and Wales, that statutory rate increased from -0.25% to +0.5% on 11 January 2025; the change did not automatically alter the Swift calculation. Broadly, a shorter life expectancy means a greater present value for the reversionary interest and potentially a smaller accommodation award. Expert evidence on lifespan and housing requirements therefore matters, and a formula should not replace individual assessment.
Smaller adaptations and equipment
The Swift property-purchase method does not ordinarily govern costs such as grab rails, access ramps, stairlifts, hoists, adapted bathrooms or specialist seating. Those are usually assessed by reference to the reasonable cost of necessary work or equipment, together with installation, servicing and future replacement where justified. Some alterations may increase the property’s value, but that does not mean their reasonable costs are automatically excluded. Occupational therapists and building specialists can identify appropriate changes. Keep quotations, invoices, receipts and photographs, especially where you have already funded urgent work yourself.
The Disabled Facilities Grant: a different route
You may also qualify for a Disabled Facilities Grant from your local council towards necessary changes to your home. In England, the standard maximum is £30,000, although councils can provide discretionary additional assistance. Grants for adults are generally means tested, considering household income and savings above applicable thresholds. Occupational therapy and council assessments help establish which works are necessary and appropriate. Rules and maximum amounts differ elsewhere in the UK.
A grant can be valuable if urgent work is needed or no compensation claim is available. However, major adaptations or a move may cost considerably more than the standard grant limit. Do not assume a £30,000 grant will cover the full cost of an extension or accessible replacement property. A personal injury claim is assessed against proven losses and reasonable future needs, rather than a fixed grant ceiling. If public funding pays for work you also claim as damages, your solicitor should address potential overlap and the specific funding rules.
Getting adaptations funded before your claim settles
Serious injury claims often take considerable time to resolve, but urgent housing needs may arise much sooner. An interim payment can sometimes release part of the expected compensation before final settlement, helping pay for accessibility work, equipment or specialist assessments. The defendant may agree voluntarily; otherwise a court application must meet legal conditions, such as an admission of liability or sufficient evidence that substantial damages are likely. An interim payment is not guaranteed, and any amount is taken into account at settlement.
Early specialist input can identify changes improving safety and independence. Planning also reduces the risk of unsuitable alterations. Our guide to how the personal injury claim process works explains how evidence, rehabilitation and interim funding fit into a serious injury case.
Time limits and funding
For most adults in England and Wales, court proceedings must begin within three years of the accident or the relevant date of knowledge, subject to important exceptions. We handle eligible claims on a no win no fee basis. If your claim isn’t successful, you won’t pay us anything. If it is successful, our fee is 20% plus VAT (24% in total), taken from the compensation you receive for your pain and suffering and for financial losses up to settlement. We never take a fee from compensation for future losses, such as future care or loss of earnings, and nothing else is deducted from your compensation. We’ll confirm all of this in writing before your claim starts. Read why accident victims shouldn’t accept an offer before speaking to a lawyer before settling without a full accommodation assessment.
Frequently asked questions
Here are some common questions about housing adaptations, accessible accommodation and serious injury compensation.
Can I claim for a bigger house, not just adaptations to my current one?
Yes, if expert evidence shows that an alternative property is reasonably necessary because your existing home cannot meet your needs, or moving is more appropriate than extensive alterations. Additional accommodation capital is generally assessed using the Swift v Carpenter approach, considering your individual circumstances.
Do I have to pay the compensation back out of my estate when I die?
No. The reversionary interest is deducted when the accommodation award is calculated. It is not a separate debt automatically recoverable from your estate, and there is no routine repayment of the award on death.
Can I get a Disabled Facilities Grant and still bring a compensation claim?
Generally, yes. However, grants and compensation relating to the same adaptation work may need to be considered together to prevent double recovery. Tell your solicitor about any assistance awarded or applied for.
What if my needs change after my claim has settled?
Most settlements are full and final, so changing needs can be difficult to fund through a settled claim. Detailed medical, housing and occupational therapy evidence is important before settlement. Special settlement arrangements are possible in limited circumstances.
Do I need a case manager or occupational therapist to support this part of my claim?
For substantial adaptations, professional assessment is usually important. Occupational therapists identify functional needs, while accommodation experts and case managers can help assess suitable layouts, costs and future arrangements. The appropriate evidence depends on your injury and proposed work.
Talk to Mark Reynolds Solicitors
Valuing home adaptations and alternative accommodation requires medical evidence, specialist costings and a clear understanding of your long-term needs. We can help assess the work required, seek suitable interim funding where available and make sure housing costs are considered before settlement. We represent eligible clients on a no win no fee basis, with terms confirmed in writing. Contact our team for a free, no-obligation conversation. Our offices are in Liverpool, Runcorn and Warrington, and we assist clients across England and Wales.
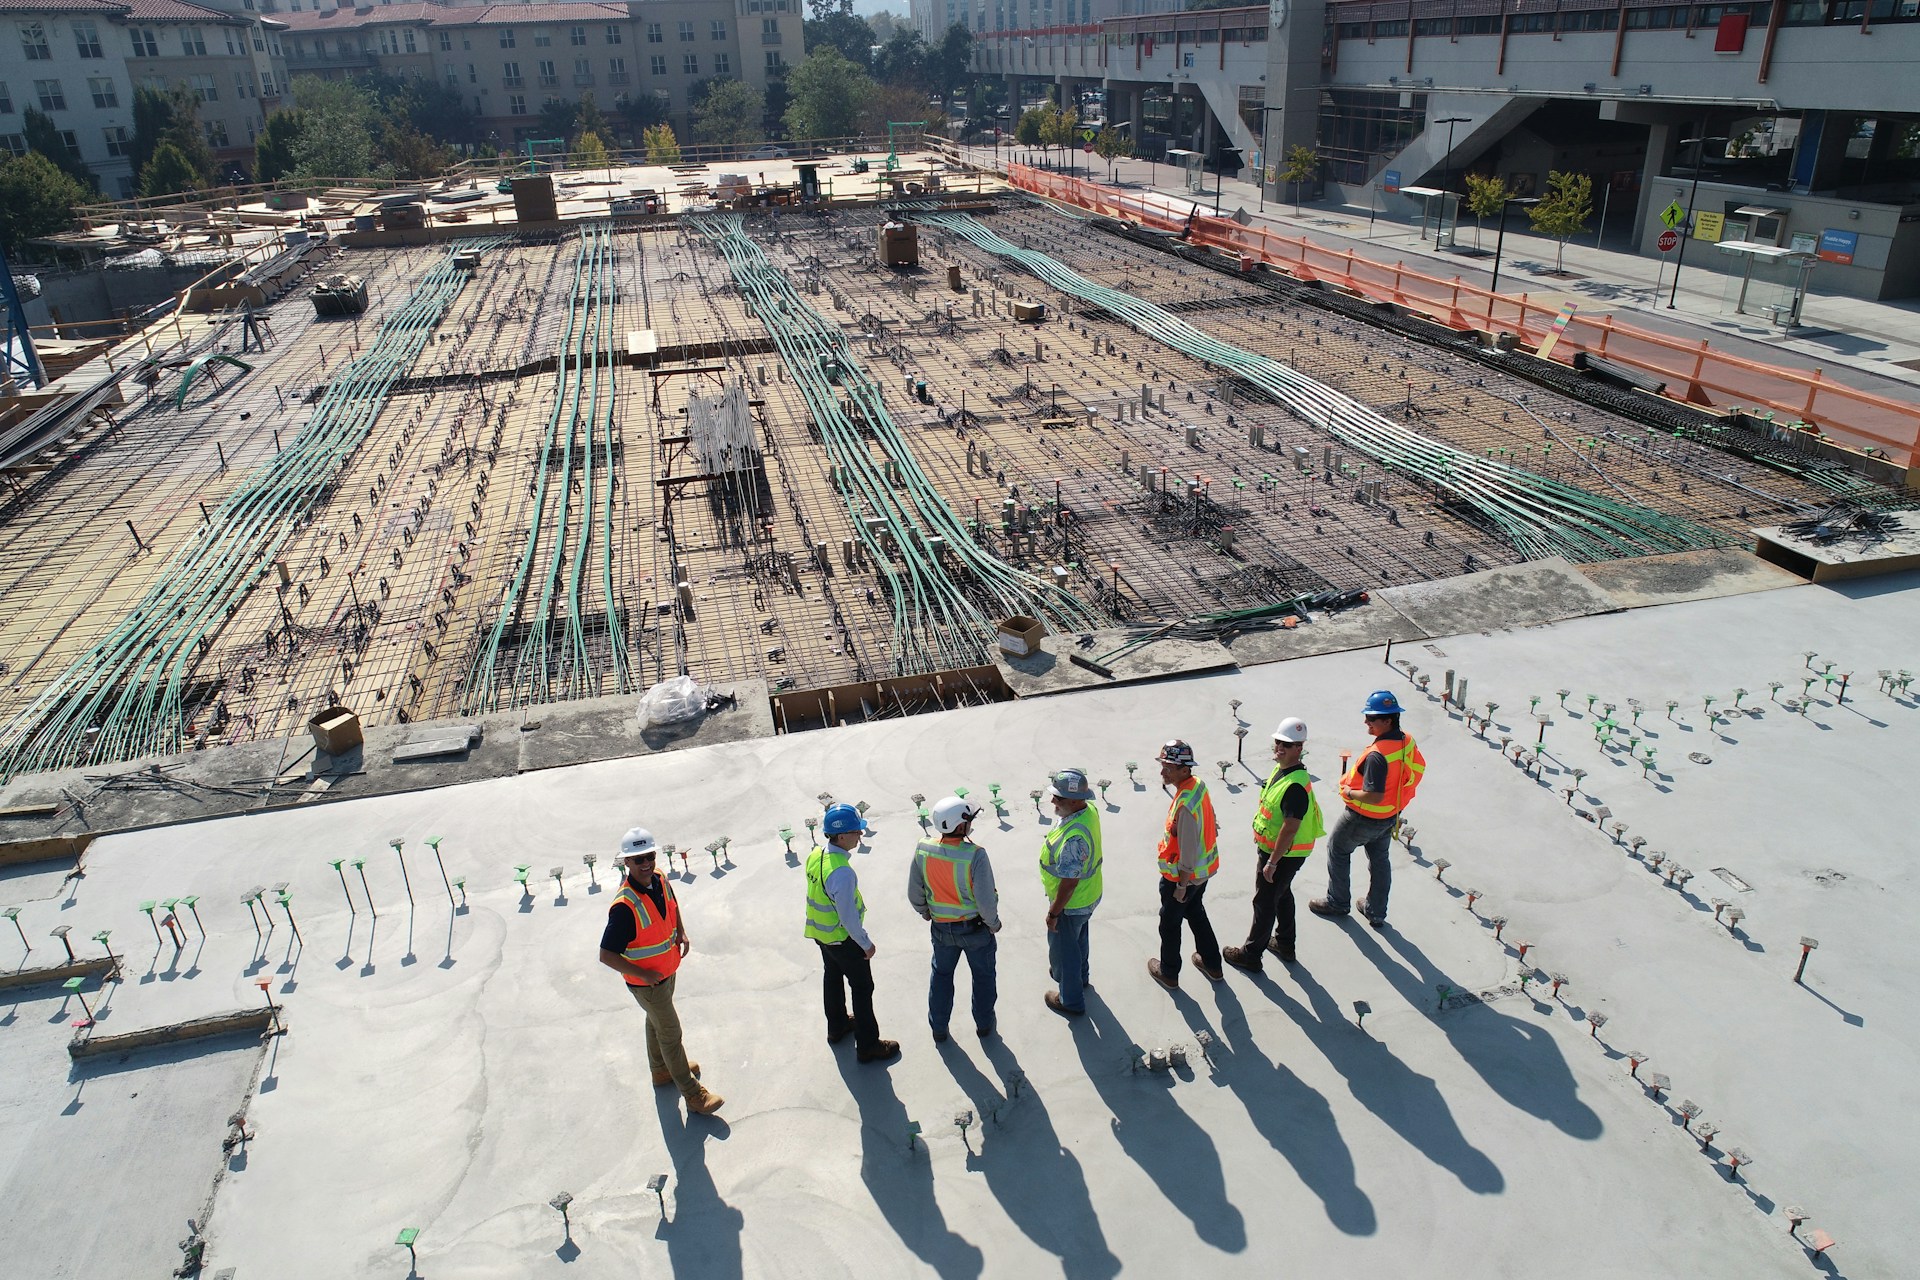
What a recent construction fall shows about serious spinal injuries at work
It was only his second week on the job. In January 2024, a 24-year-old labourer working for a scaffolding company on a West Yorkshire housing development stepped backwards through an unprotected stairwell opening and fell one storey onto concrete. He sustained serious spinal injuries and has not returned to physical work. The housebuilder, Hillbeck Homes (Sowerby Bridge) Ltd, was fined £300,000 in September 2026 after an HSE investigation identified failures in planning, supervision and fall prevention. The case illustrates how a familiar building-site hazard can cause life-changing injuries, and why responsibility for workplace safety may extend beyond the injured person’s direct employer.
What happened in Sowerby Bridge
A 24-year-old labourer and father of one was working temporarily for a scaffolding company on a site where Hillbeck Homes (Sowerby Bridge) Ltd was building four houses. The incident happened in January 2024, during his second week there. He stepped backwards through an opening intended for a staircase that had not yet been fitted and fell one storey onto the concrete floor below.
The stairwell opening had previously been covered by loose scaffold boards, but these had been removed, leaving no secure cover or protective barrier around the edges. There was no alternative access to the lower floor. The 24-year-old labourer lost consciousness in the fall and was rescued by West Yorkshire Fire and Rescue Service and a specialist Hazardous Area Response Team. His spinal injuries prevented him working for months, and HSE reported in September 2026 that he had not returned to a physically demanding job.
What HSE’s investigation found
The open stairwell posed a foreseeable fall risk. HSE found that Hillbeck Homes had not put adequate fall-prevention measures in place. The company was found guilty of three charges arising from failures to plan work at height properly, provide appropriate supervision and take suitable and sufficient precautions against falls. The investigation identified deficient site arrangements and missing physical safeguards.
Simple measures could have prevented the fall. Securing a properly designed cover over the opening, or installing suitable edge protection, would have addressed the exposed hazard. HSE Inspector Louise Redgrove described the incident as wholly avoidable and linked it to basic shortcomings in planning and supervision. A risk assessment on paper is not enough if the protective measures are removed and nobody ensures they are reinstated.
The legal outcome, and who was actually held responsible
On 16 September 2026, Leeds Magistrates’ Court fined Hillbeck Homes (Sowerby Bridge) Ltd £300,000 and ordered it to pay £9,284.05 in prosecution costs. HSE announced the outcome on 21 September 2026.
The 24-year-old labourer was employed by a scaffolding business, not Hillbeck Homes. Nevertheless, the prosecution was brought against the housebuilder responsible for the failures identified by HSE. This distinction matters: health and safety obligations can extend to workers employed by other organisations. A prosecution does not itself establish liability in a civil claim.
Construction work commonly involves developers, principal contractors, subcontractors and agency workers. Their duties depend on their roles and the activities or areas they control. Under the Construction (Design and Management) Regulations 2015, principal contractors must coordinate health and safety during the construction phase, while individual contractors must manage risks arising from their own work. An employer’s duties also remain relevant. Our guide to employer duties under the Health and Safety at Work Act explains the wider framework. If an injured worker makes a civil claim, the evidence must show which parties owed a duty, how it was breached and whether that breach caused the injury.
The safety standard this case highlights
The Work at Height Regulations 2005 require work at height to be properly planned, appropriately supervised and carried out safely by competent people. The hierarchy of control is to avoid work at height where reasonably practicable, prevent falls where the work cannot be avoided, and minimise the distance and consequences of any fall that cannot be prevented. They apply to floor openings as well as scaffolding and platforms.
Depending on the work, appropriate controls might include fixed or securely fitted covers, guardrails, barriers and safe access routes. Those protections must remain effective as trades move through the site. If a cover is temporarily removed, there needs to be a controlled system for protecting the opening and restoring the safeguards. Training and written instructions cannot substitute for suitable physical protection where it is reasonably practicable.
If you’ve suffered a spinal injury from a fall at work
Falls can involve open floors and roofs, missing edge protection, unsuitable ladders, defective working platforms or unguarded excavations. The important questions are whether the risk was foreseeable, who controlled the relevant work and what reasonable steps were taken to prevent it. A serious injury does not itself prove negligence, but failures in inspection, training, access arrangements or supervision may provide evidence of a breach of duty.
Do not assume your claim can only be against the business named on your payslip. An agency worker or subcontractor may have a potential claim against an employer, principal contractor or another party whose acts or omissions contributed to the accident. Responsibility is assessed individually, and more than one defendant may be involved. Our guide to making an accident at work claim explains the usual steps. Our article on which spinal injuries you can claim for discusses conditions ranging from spinal fractures and nerve damage to injuries causing permanent loss of mobility.
A spinal injury’s full effects may not be apparent immediately. Pain, neurological symptoms, rehabilitation needs and the ability to return to work can change over time. Medical evidence from an appropriate specialist may be needed before compensation can be assessed fairly, particularly where future treatment, care or earnings losses are involved. Our explanation of how the personal injury claim process works outlines this process. Preserve photographs, incident reports, medical records and witnesses’ details, and record how your symptoms affect daily life and employment.
Time limits and funding
In England and Wales, most adult personal injury claims must be brought within three years of the accident or the later date of knowledge, with exceptions. An HSE investigation or prosecution does not stop this clock. Different rules can apply to children and people lacking litigation capacity. We offer eligible claims on a no win no fee basis, with no upfront solicitor’s fee. We explain possible deductions and costs before you sign.
Frequently asked questions
Common questions about spinal injuries following falls at work.
I wasn’t employed directly by the company controlling the site. Can I still claim against them?
Potentially, yes. A principal contractor or another business controlling the relevant work may owe legal duties to people employed by other organisations. Whether you have a claim depends on the duties owed, the evidence of any breach and whether it caused your injury.
If HSE prosecutes my employer or the site controller, do I still need my own claim?
Yes. A criminal prosecution concerns breaches of safety law, and any fine is not compensation paid to the injured worker. To recover damages for injury, lost earnings or care needs, you normally need a separate civil claim, whether settled by agreement or decided by a court.
How serious does a fall have to be before I can claim?
There is no minimum height. What matters is whether another party breached a duty of care and caused a compensable injury. Even short falls can cause serious harm.
Can I claim if I was partly at fault, for example if I stepped somewhere I shouldn’t have?
Possibly. An employer or other dutyholder may still be responsible for failing to protect a foreseeable hazard. If you contributed to the accident, a court may reduce damages for contributory negligence. The outcome depends on the evidence; responsibility is not decided solely by where you stepped.
How long does a spinal injury claim usually take?
There is no standard timescale. Claims involving severe or uncertain spinal injuries may take longer because medical specialists need to assess recovery, care requirements and future losses. Liability disputes and rehabilitation can also affect the timetable. Some cases resolve sooner, while complex claims may take years.
Talk to Mark Reynolds Solicitors
This case shows why preventing falls is essential and why safety responsibilities can extend beyond a worker’s direct employer. If you or someone close to you has suffered a spinal injury after a fall at work, including at a construction site operated by another business, Mark Reynolds Solicitors can assess the circumstances and explain who may be responsible. We handle eligible cases on a no win no fee basis, with terms explained at the outset. We take instructions from clients nationwide and have offices in Liverpool, Leigh, Runcorn and Warrington. Call us on 0800 002 9577 to speak to our team.
What the Knowsley conveyor injury case shows about machinery safety at work
A maintenance engineer working a night shift at a factory on Knowsley Industrial Park reached through a hole cut into the side of a running conveyor to clear a blockage. His arm was pulled into the machine. There was no guard in place and no emergency stop button in the area, and because he was working alone, he could only wave at a CCTV camera for help before freeing himself after around 40 seconds. Factory Services UK Limited has since been fined £160,000 after an HSE investigation and a guilty plea. The case is a stark, local reminder of what proper machinery guarding is for, and what happens when it is missing.
What happened at Knowsley Industrial Park
On 18 March 2025, a maintenance engineer was working a night shift at Factory Services UK Limited’s animal-feed site on Moorgate Road, Deacon Park, Knowsley Industrial Park, when he was asked to look at a problem with a conveyor. While it was still running, he reached through a hole in the side of the conveyor casing to clear away some material. His arm was drawn into the moving machinery.
There was no guard in place and no emergency stop button in the area. Working alone, with nobody nearby to see or hear what had happened, he repeatedly waved at a CCTV camera in the hope that whoever was monitoring it would notice and raise the alarm. Nobody did. After around 40 seconds, he managed to free his arm himself.
The maintenance engineer suffered catastrophic injuries to his forearm and hand, including a fracture and extensive degloving. He needed multiple operations and blood transfusions, continues to receive specialist treatment, and remains unable to return to work.
What HSE’s investigation found
The detail that makes this case worth pausing on is not just the accident itself, but how long the danger had existed. HSE’s investigation established that the hole in the conveyor casing had been cut years earlier so workers could clear blockages while the machine kept running, rather than stopping it properly. A second conveyor on the same site was found to have a similar unauthorised access point.
This had happened despite the company’s own safe systems of work requiring machinery to be guarded and isolated before any maintenance or cleaning. It had also gone unnoticed through routine inspections, management walkarounds and audits. That is perhaps the most important lesson here for any employer. Having a safe system of work written down, and regularly checking the workplace, is not the same as that system actually being followed on the shop floor, shift after shift, when nobody senior is watching.
The legal outcome, and what a fine does and does not do
Factory Services UK Limited pleaded guilty to breaching Section 2(1) of the Health and Safety at Work etc. Act 1974, the core duty an employer owes to protect its own staff. At Warrington Magistrates’ Court on 8 September 2026, the company was fined £160,000 and ordered to pay costs of £4,728.
It is worth being clear about what that fine represents, because this is a point people often misunderstand. The £160,000 was a criminal penalty, paid to the state as punishment for breaking the law and to deter similar failures. It is not compensation, and none of it goes to Mr Slinger for his own injuries, lost income, treatment, care or future needs.
We are not instructed in Mr Slinger’s case, and nothing here should be read as a comment on it specifically. But as a general point, where an HSE prosecution follows a workplace injury like this, the injured worker may also have a separate right to bring a civil claim for compensation against their employer, entirely independent of whatever criminal penalty the court imposes.
The safety standard this case highlights
Beyond the general duty under the 1974 Act, the detailed standard for machinery like this sits in Regulation 11 of the Provision and Use of Work Equipment Regulations 1998, usually known as PUWER. It requires employers to take effective measures to prevent access to dangerous parts of machinery, or to stop those parts moving before anyone can reach them. It also sets out a clear order of protection: fixed guards first, then other guards or protection devices such as interlocks, then other protective measures, with training and instruction supporting the system rather than replacing it.
A hole deliberately cut into a guard so a job could be done slightly faster is about as direct a breach of that hierarchy as it gets. It is also a pattern that comes up again and again in machinery accident cases, where a guard has been removed, propped open or modified over time to save a few seconds, and the shortcut becomes normalised long before anyone is hurt by it.
If you’ve been hurt in a conveyor belt or machinery accident at work
Most conveyor and machinery accidents we see share a handful of causes, and each points to a specific failure in your employer’s duties under the Health and Safety at Work Act.
- Missing, removed or defeated guarding around moving parts, pinch points or rollers
- No emergency stop within easy reach of where people actually work
- Being expected to clear blockages or carry out maintenance without the machine being properly isolated first
- Inadequate training on a specific machine, especially after it has been modified or replaced
- Being left to work alone on hazardous equipment with no effective way to raise an alarm
If any of these contributed to your accident, you may well have a valid accident at work claim. As with any work accident claim, a few of the common mistakes people make with a work accident claim are worth avoiding, chief among them not gathering evidence early enough. Photographs of the machine and any guarding, the names of anyone who saw what happened, and a copy of the accident book entry all matter, and your solicitor can also seek maintenance records, risk assessments, training records and any relevant RIDDOR paperwork once your claim is under way.
Time limits and funding
You generally have three years from the date of the accident to start court proceedings, under the Limitation Act 1980, though this can run separately from any HSE investigation or prosecution. The HSE process follows its own timetable and does not pause your own civil claim deadline.
Claims like this are commonly handled on a no win no fee basis, so there is no upfront legal cost to finding out where you stand, and how the personal injury claim process works is worth reading if you want a fuller picture before you call.
Frequently asked questions
A few of the questions we are asked most often about conveyor belt and machinery accidents at work.
If HSE prosecutes my employer, do I still need to make my own claim?
Yes. An HSE prosecution and fine is a separate criminal matter between HSE and your employer. It does not compensate you, and you will still need to bring your own civil claim to recover compensation for your injury and losses.
Can I claim if I was partly to blame, for example for reaching into the machine myself?
Often, yes. If your employer failed to guard the machine properly, provide an emergency stop, enforce isolation procedures or give adequate training, you may still have a claim even if your own actions played some part. Your compensation could be reduced to reflect any contributory negligence, but that does not automatically defeat the claim.
What if the machine has since been fixed or modified?
This does not affect your right to claim for what happened before the fix. What matters is the condition of the machine, the safe system of work and the employer’s risk control at the time of your accident. Early photographs, witness evidence and maintenance records can be important if the machine has changed since.
Does it matter if I was an agency worker or contractor rather than a direct employee?
Not necessarily. Whoever controlled the workplace, the system of work and the machinery may owe duties to people working there, whatever their employment status. The detail depends on the contract, the site arrangements and who had practical control over the risk.
How much compensation could I get for a serious hand or arm injury?
This depends entirely on the severity and long-term impact of your injury. Your solicitor will value the injury using medical evidence alongside the Judicial College Guidelines, then add your actual financial losses, such as lost earnings, treatment, care, equipment and future support.
Talk to Mark Reynolds Solicitors
Cases like the one at Knowsley are a reminder that serious machinery accidents are rarely a one-off stroke of bad luck. They usually trace back to a guard that was missing, a shortcut that became routine, or a system that looked fine on paper but was not being followed in practice. If you have been hurt by a conveyor belt or other machinery at work, we can help you understand whether your employer’s failings contributed, and what your claim could be worth. We act on a no win, no fee basis. Contact our team for a free, no obligation conversation. We take instructions from clients nationwide and have offices in Liverpool, Leigh, Runcorn and Warrington. Call us on 0800 002 9577 to speak to our team.
How unpaid care from family and friends is treated in a serious injury claim
When a family member or friend gives up their time, sometimes years of it, to look after you after a serious injury, that sacrifice has a real financial value, and English law recognises it. This is known as a gratuitous care claim, and it lets you recover compensation for unpaid help you have reasonably needed because of your injuries, calculated by reference to the cost of paid care. In a serious injury claim, gratuitous care is often one of the largest single elements of the final settlement, not a minor add-on.
What is gratuitous care, and can you really claim for it?
Yes, you can. English law has recognised this since the 1970s, when the courts confirmed in Donnelly v Joyce that an injured person can recover the value of care provided to them free of charge by a relative or friend, as part of their own compensation. It does not matter that no money actually changed hands between you and your carer. The law treats the need for that care as a genuine consequence of the accident.
Gratuitous care typically covers things like help with washing, dressing and eating, preparing meals, housework, driving you to medical appointments, and general supervision if you are not safe to be left alone. It sits alongside other financial losses in your claim, such as lost earnings, and you can read more about how the personal injury claim process works more broadly. Gratuitous care is simply one of the heads of loss assessed within it, and in a serious or catastrophic injury claim it is usually calculated with input from a care expert rather than estimated informally.
How gratuitous care is valued
There is a fairly standard method, even though every case is assessed on its own facts. Your solicitor, often with input from a care expert, works out roughly how many hours of extra help you have needed each week, then applies an hourly rate based on what suitable paid care would cost for similar support. A discount, commonly around 25%, is then taken off that commercial rate. The discount reflects the fact that unpaid family care does not carry the same tax, National Insurance, agency overheads or travel costs as commercial care.
| Step | What happens |
|---|---|
| 1. Hours | Work out how many extra hours of help you needed each week, above what would have been normal before the accident |
| 2. Rate | Apply an hourly rate based on local commercial care charges for similar support |
| 3. Discount | Deduct a suitable percentage, commonly around 25%, to reflect the costs a family carer does not incur |
| 4. Total | Multiply the discounted rate by the hours, then by the number of weeks or years the care has been, or will be, needed |
A rough example helps make this concrete. Ten hours a week at a commercial rate of £20 an hour comes to £200. After a 25% discount, that is £150 a week, or around £7,800 over a year. Multiplied across several years of a serious injury claim, this single head of loss can run into a significant sum.
Why the compensation is legally meant for your carer
This is where gratuitous care claims differ from most other heads of loss. In Hunt v Severs, the House of Lords confirmed that although you, as the injured claimant, formally recover this money from the defendant, you hold it on trust for whoever actually provided the care. In practice, that usually means passing it on to the family member or friend who gave up their time.
This matters for two reasons. First, it is a recognition, in financial terms at least, of what your carer has genuinely given up, whether that is paid work, free time or their own wellbeing. Second, if you are setting up a personal injury trust to protect a larger settlement, for example to avoid it affecting means-tested benefits, the gratuitous care element should be discussed carefully with your solicitor.
The one situation where you cannot claim
There is a significant exception. If the person who cared for you is also the person who caused your accident, for example a partner who was driving the car at the time of a crash, you cannot normally claim for the care they personally provided. The reasoning is straightforward once you see it. The defendant would effectively be paying themselves, since the money would be held on trust for the very person responsible for the claim in the first place.
This does not affect your right to claim for every other element of your injury, and it does not prevent a claim for care provided by someone else, such as another relative who stepped in.
What counts as “above and beyond”, and how to prove it
Not every bit of help a family member gives you counts. The care being claimed needs to go beyond what that person would ordinarily have done for you anyway, or the usual give and take of family life. A partner doing the weekly shop they always did is not a loss caused by the accident. A partner doing the shop, plus washing and dressing you, plus driving you to three appointments a week, plainly is.
Because this is among the heads of loss most often challenged in a personal injury case, decent evidence matters.
- A day-to-day care diary kept by you or your carer, ideally started soon after the accident
- A witness statement from the person who provided the care, describing what they actually did
- Independent medical or care expert evidence confirming the level of care was reasonably necessary
- Being accurate rather than generous with the hours claimed, since overstating this can undermine your credibility on the rest of your claim too, as our note on fundamental dishonesty in personal injury claims explains
Future care: when gratuitous family care is not the long-term answer
For a short recovery, ongoing family care usually makes sense for everyone. For a catastrophic or lifelong injury, it often does not, and your solicitor and any care expert involved will think this through carefully. A family member who has provided intensive care for two years while a claim is resolved may not be able to sustain that for the next 30, whether because of their own age, health, work, family responsibilities or the toll it takes.
Courts and insurers both recognise this. Claims involving long-term future care frequently move toward a mix of continued family involvement and professional, paid support, costed and valued separately within your serious injury claim rather than assumed to continue indefinitely for free. Getting this balance right, rather than rushed, is one of the reasons these claims often take real time to settle properly.
Frequently asked questions
A few of the questions we are asked most often about claiming for unpaid care.
Can I claim for care given by a friend, not just family?
Yes. The principle applies to anyone who has provided genuine, unpaid care because of your injury, whether that is a partner, parent, sibling, or a close friend who stepped in.
Do I have to pay my carer back from the compensation?
The compensation for this element of your claim is legally held on trust for the carer, so yes, in principle it should be passed on to them. The practicalities can be discussed with your solicitor, especially where the wider settlement is being structured carefully.
What if my carer already helped me with some things before the accident?
Only the additional care caused by your injury counts. Help that was already part of your normal family life beforehand is not included.
Can I claim for emotional support, not just physical help?
A gratuitous care claim generally covers practical tasks, assistance and supervision rather than emotional support on its own, though the broader impact on you and your family may be reflected elsewhere in your claim.
How far back can I claim for care already provided?
You can claim for reasonable care provided since the date of the accident, which is one reason it helps to start keeping a record of hours and tasks as early as possible.
Does receiving this money affect my carer’s own benefits or tax position?
This depends on individual circumstances, so it is worth raising with your solicitor directly if your carer receives means-tested benefits, or if there may be tax or financial planning issues, before any settlement is finalised.
Talk to Mark Reynolds Solicitors
If a family member or friend has given up their time to look after you following a serious injury, that deserves to be properly recognised and valued, not treated as an afterthought in your claim. We act on a no win, no fee basis and will talk you through what the care you have received is likely to be worth, and how to start keeping the right evidence from today. Contact our team for a free, no obligation conversation. We take instructions from clients nationwide and have offices in Liverpool, Leigh, Runcorn and Warrington. Call us on 0800 002 9577 to speak to our team.
Why serious injury claims can take longer to settle
Serious injury compensation has to reflect a lifetime of costs and losses, not just the next few months, so your solicitor needs a complete and accurate picture of your recovery, prognosis and future needs before your claim can be valued properly. Settling early, before that picture is clear, risks accepting far less than you are entitled to. Depending on the type and severity of the injury, many serious injury claims take somewhere between eighteen months and five years to reach a final settlement, and the most complex cases can take longer.
How long does a serious injury claim actually take?
There is no single answer, because it depends on the injury, whether liability is disputed, how long it takes for your condition to stabilise, and how much evidence is needed to value future losses. As a general guide, many serious injury claims settle within eighteen months to five years. A moderate road traffic injury with liability admitted early may resolve more quickly, while a catastrophic brain or spinal injury claim can reasonably take three to five years or longer.
| Type of claim | Typical time to settle | Main reason for the timescale |
|---|---|---|
| Road traffic injury, moderate severity, liability admitted early | 12 to 18 months | Still needs time for the injury to stabilise before it can be valued |
| Workplace injury, liability accepted | 12 to 24 months | Can extend if there is a parallel HSE investigation or complex employment evidence |
| Amputation or limb loss | 2 to 4 years | Prosthetics, rehabilitation and lifelong care costs all need to be quantified |
| Spinal cord injury | 3 to 5 years or more | Long-term prognosis, accommodation and care needs take time to establish with confidence |
| Traumatic brain injury | 3 to 5 years or more | Cognitive, behavioural and personality effects can take years to fully emerge |
| Clinical negligence involving serious injury | 3 to 6 years | Breach of duty and causation must both be proven, often making these slower claims |
| Fatal accident claim | 2 to 5 years | Dependency calculations, estate claims and multiple family claims can add complexity |
These are general guides rather than promises, and your own solicitor will be able to give you a clearer estimate once they understand the specifics of your case.
Why your claim waits for “maximum medical improvement”
The single biggest factor in how long a serious injury claim takes is not always the legal process itself. It is your recovery. Solicitors often describe the point at which your condition has stabilised, whether that means a full recovery or a settled long-term prognosis, as reaching maximum medical improvement. Settling before that point is one of the more common and costly mistakes people make with personal injury claims. Once you accept a final settlement, you generally cannot go back for more if your condition later worsens.
For a broken wrist, that might take a few months. For a serious brain injury, doctors may need two years or more before they can say with confidence how your memory, concentration, personality or ability to work will be affected long term, and how much ongoing support you will need. Rushing that assessment to speed up your claim rarely works in your favour, which is exactly why we usually advise against accepting an early offer without speaking to a solicitor first.
Interim payments and the Rehabilitation Code: support while you wait
You do not necessarily have to wait years with no support at all. Two mechanisms exist specifically to help with this.
An interim payment is a sum released by the defendant or their insurer before your claim finally settles. It is usually available where liability has been admitted, judgment has been entered, or the court is satisfied that you are likely to recover substantial damages. It can help with urgent needs such as private treatment, home adaptations, care, equipment or lost income, and your solicitor can request one once the liability position is clear enough.
Separately, the Rehabilitation Code 2015 encourages your solicitor and the insurer to consider your rehabilitation needs early, often before the final value of the claim is resolved. It is voluntary rather than a legal requirement, but it is recognised in the pre-action protocol for personal injury claims and is widely used in appropriate cases. Insurers often cooperate because getting treatment and support in place earlier can improve recovery and reduce the overall cost of the claim.
Why compensation is sometimes paid as regular payments, not a lump sum
For the most serious, lifelong injuries, a single lump sum is not always the right way to structure compensation, and the court has a say in this. Under section 2 of the Damages Act 1996, a court can order that some or all future financial losses are paid as regular payments, known as a periodical payments order, rather than as one upfront sum.
The appeal is straightforward. Life expectancy, and the future cost of care, therapy, case management and specialist equipment, can be genuinely difficult to predict decades in advance. A lump sum that looks generous today could fall short in twenty years if costs rise faster than expected, or if you live longer than assumed. Periodical payments reduce that risk by providing ongoing payments for future needs.
This is one reason working out the true value of a catastrophic injury claim, and agreeing how it should be paid, takes considerably longer than settling a straightforward injury with a single cheque. It also explains why the personal injury discount rate used in England and Wales to calculate lump sum future loss awards, currently 0.5 per cent, matters so much to how these cases are valued and negotiated.
Other reasons these claims take time
Beyond your own recovery, a handful of other factors commonly add to the timeline of a serious injury claim.
- Disputed liability. If your employer, the other driver or an NHS trust disputes responsibility, or argues you contributed to your own injuries, resolving that argument can take months or years on its own.
- Multiple experts. Catastrophic claims often need input from several specialists, such as neurologists, orthopaedic surgeons, care experts, occupational therapists, accommodation experts and employment consultants. Their reports have to be prepared, exchanged and sometimes challenged.
- Court timetables. Only a minority of claims reach trial, but where a case does proceed to court, waiting for directions, expert evidence and a listed hearing date can add months.
- Multiple insurers or defendants. Claims involving more than one responsible party, such as a multi-vehicle collision or workplace accident involving contractors, mean more parties who all have to agree before anything can be finalised.
Clinical negligence claims often take even longer
Clinical negligence claims involving serious injury tend to sit at the slower end of the range, often taking three to six years. Unlike many accident claims, where the fact of the accident may be clearer, a clinical negligence claim has two separate hurdles to clear. You need to show the treatment fell below an acceptable standard of care, known as breach of duty, and separately that this specific failure caused the harm you suffered, known as causation.
Both stages usually require detailed expert medical evidence, and the defendant may obtain its own evidence before a final position is reached. NHS Resolution, which handles claims against NHS organisations in England, also has its own processes and timescales to work through. You can read more about how long a medical negligence claim takes if this applies to your situation.
What happens if the claim ends up going to court
Very few serious injury claims are finally decided by a judge. Most settle through negotiation once both sides have enough medical and financial evidence to understand the likely value of the claim. You can read more about how the personal injury claim process works and the settlement process for personal injury claims more generally.
Where a genuine dispute remains, whether over liability, contributory negligence, or the value of future losses, court proceedings create a more structured timetable, with deadlines for evidence and a trial date at the end of it. The prospect of a trial date often does more to bring a reluctant insurer to a sensible offer than months of correspondence, and our note on what happens if you lose a personal injury claim covers the other side of that risk.
The three-year time limit still applies
Whatever the eventual timeline turns out to be, you generally still need to start court proceedings within three years of the accident, or within three years of the date of knowledge in many clinical negligence and industrial disease claims, under the Limitation Act 1980. This deadline exists independently of how long your claim then takes to resolve once it has begun. There are important exceptions for children and people who lack mental capacity to bring a claim themselves, and the court has a limited discretion in some cases, but the safest approach is to get advice early.
Getting a solicitor involved early does not force a quick, undervalued settlement. It simply means the evidence gathering, rehabilitation and expert reports can start sooner, which often makes the whole process smoother rather than slower.
Frequently asked questions
A few of the questions we are asked most often about how long serious injury claims take.
How long does a brain injury claim take to settle?
Traumatic brain injury claims are among the longest-running personal injury cases, typically taking three to five years or more in serious cases. The long-term effects on memory, concentration, personality, care needs and future earning capacity can take years to fully emerge, and settling too early risks significantly undervaluing the claim.
What is an interim payment and how do I get one?
An interim payment is money released by the defendant or insurer before your claim fully settles, usually once liability is admitted or your solicitor can show there is a strong basis for it. It helps cover urgent costs such as treatment, care, home adaptations or lost income. Ask your solicitor whether you are likely to be eligible.
Will I have to go to court?
Most claimants never set foot in a courtroom. The large majority of serious injury claims settle through negotiation, and even where court proceedings are formally started, many still settle before a trial actually takes place.
Does no win no fee affect how long my claim takes?
No win no fee funding does not change the medical or legal evidence needed to value the claim properly. Under a no win no fee agreement, your solicitor takes on the financial risk of the case rather than being paid regardless of outcome. The claim should still take as long as it genuinely needs to take.
How much compensation will I get for a serious injury?
This depends entirely on the injury and its long-term impact. Solicitors refer to the Judicial College Guidelines as a starting point for valuing pain, suffering and loss of amenity, before adding your specific financial losses, future care, treatment, equipment, lost earnings and other needs on top.
Can I claim if the accident happened more than three years ago?
Generally, the three-year limitation period is a strict deadline, but there are exceptions for children, people who lack mental capacity, and cases where the date of knowledge of an illness, injury or negligence came later than the incident itself. If you are close to or beyond three years, take advice immediately rather than assuming the claim is impossible.
Talk to Mark Reynolds Solicitors
A long timeline is not a sign that anything has gone wrong. For a serious injury, it usually means your solicitor is doing the job properly, making sure your compensation reflects the whole of your future rather than a rushed guess at it. We act on a no win no fee basis, and we will give you a realistic view of how your particular claim is likely to progress from the very first conversation. Contact our team today for a free, no obligation chat. We have offices in Liverpool, Leigh, Runcorn and Warrington, and we are happy to talk whenever you are ready.
When your employer says you caused your own accident at work
If your employer or their insurer has told you that an accidents at work claim was your own fault, that does not automatically end things. Compensation claims for workplace accidents in England and Wales are fault based, so you usually need to show some element of employer negligence. But responsibility for an accident rarely sits entirely with one person. If your employer’s failings played any part, whether that is inadequate training, a missing guard on a machine or poor supervision, you may still have grounds to claim, even where your own actions contributed too.
Can you claim if it was your fault?
In most cases, no, if the accident was entirely down to your own actions with no failing on your employer’s part at all. That situation is rarer than many people assume, though. If your employer contributed in any way, through inadequate training, a missing risk assessment, faulty equipment or poor supervision, you may still have a valid accident at work claim, even where you also played a part in what happened.
Solicitors call this a fault-based system. It works differently from the no-fault schemes some other countries use, where an injury at work is covered regardless of who caused it. Here, you need to show your employer breached the duty of care it owes you, whether that comes from the general common law duty to provide a safe system of work, or specific statutory duties such as those set out in the Health and Safety at Work etc. Act 1974. Those duties cover everything from training and supervision to the condition of equipment and the way work is planned, and they apply whether you were hurt in a factory, on a construction site, in a warehouse or operating a forklift.
What actually counts as “your fault”?
Employers and insurers often use the word fault loosely. There is a real difference between an honest slip while following the system you were trained in, a mistake caused by inadequate training or supervision, and conduct that is genuinely reckless, such as deliberately ignoring a clear and recent safety instruction.
In our experience working with people who have been hurt at work, most accidents sit somewhere in the middle. A worker rushes because the workload set for the shift was unrealistic. A guard is missing from a machine because maintenance was delayed. Instructions were given once, months earlier, with no refresher since. None of this excuses risk taking on your part, but it does mean your employer is unlikely to be entirely blameless, even if their first reaction is to point the finger back at you.
These sit among the common accidents at work we see time and again, and a closer look at what actually happened usually tells a more balanced story than the first assumption does. It is also worth being clear on a distinction that gets lost quickly. An accident being partly caused by your own actions is legally very different from it being entirely your fault. The law has a specific name for that middle ground.
Contributory negligence: partly at fault does not mean no compensation
If you were partly to blame but your employer’s negligence also played a part, you can usually still claim. Under the Law Reform (Contributory Negligence) Act 1945, your compensation is reduced by a percentage reflecting your share of responsibility, rather than refused altogether. A claim otherwise worth £40,000 with a 25% contributory negligence finding would typically be settled at £30,000.
This usually surfaces once you have already reported the accident and a claim is underway. Your solicitor sends a letter setting out what happened and who is responsible. The employer’s insurer then has to respond, and broadly has three options: accept full responsibility, reject the claim and provide reasons, or accept partial responsibility while arguing you should shoulder some of the blame too. You can read more about how the personal injury claim process works from that point.
There is no fixed formula for working out the reduction. It depends on how much your actions contributed to the accident happening at all, or to how serious your injuries turned out to be. The ranges below give a general sense of how this can play out in practice, though every case is judged on its own facts.
| Your part in what happened | Typical reduction in compensation |
|---|---|
| A minor lapse in concentration while otherwise following a safe system of work | 0% to 15% |
| Not using PPE you had been trained and equipped to use | 10% to 25% |
| Ignoring a clear, recent safety instruction | 25% to 50% |
| Deliberately unsafe or reckless conduct unrelated to your job | Claim may fail entirely |
These figures are illustrative rather than guaranteed outcomes. A court, or an insurer negotiating a settlement, weighs what is fair given everything that happened, not just one factor taken in isolation.
Why your employer or their insurer might say it was your fault
It is worth being a little sceptical of an early, informal verdict from your employer or their insurer. An insurer has a straightforward financial interest in reducing or avoiding a payout, and raising contributory negligence, or denying liability outright, is a common opening position rather than a final legal conclusion. Your employer, meanwhile, may genuinely believe the accident was your fault, particularly if accepting otherwise means admitting a gap in their own training or safety systems.
This is one of the more persistent personal injury claims myths: the idea that being told you were at fault settles the matter. It does not. One of the most common mistakes people make with a work accident claim is accepting that verdict at face value and not pursuing things further, when an independent look at the training records, maintenance logs or witness accounts might tell a different story.
What to do if you are told the accident was your fault
A few practical steps make a real difference to how your position looks later, whatever the eventual split of responsibility turns out to be.
- Report the accident promptly and accurately, and make sure it goes in the accident book. For certain serious injuries, your employer may also have a legal duty to notify the Health and Safety Executive under RIDDOR, regardless of who was at fault.
- Stick to the facts when you give your account. Do not speculate about who was to blame, and do not sign anything an insurer sends you without getting advice first.
- Gather what evidence you can. Photos, witness contact details and CCTV footage tend to disappear or get overwritten quickly, so acting early matters.
- Keep a record of any time off, medical appointments and lost income, since this becomes part of your evidence for a loss of earnings claim later on.
- Be straightforward about your own role in the accident from the outset. Understating it can be used against your credibility later, and our note on fundamental dishonesty in personal injury claims explains why that risk is worth taking seriously.
- Speak to a solicitor early. Many firms, including ours, work on a no win no fee basis, so getting advice at this stage costs you nothing upfront.
Could you be disciplined or dismissed?
A compensation claim and a disciplinary process are two separate things, even though they can run alongside each other. Your employer can still investigate the accident and, in serious cases, take disciplinary action if your conduct amounted to genuine misconduct or gross negligence. An honest mistake made while following normal procedure is a different matter, and a fair employer should follow a proper process rather than jumping straight to a warning or dismissal.
If you are worried about your job on top of everything else, it is worth reading about your broader rights after an accident at work, and specifically whether you can be sacked after an accident at work that was partly or mainly down to you. Being at fault for an accident does not, on its own, give your employer a free pass to dismiss you unfairly.
How long do you have to make a claim?
You generally have three years from the date of the accident to start court proceedings, under section 11 of the Limitation Act 1980. This deadline is strict. Miss it, and your claim is very likely to become statute barred, meaning the court can refuse to hear it at all, regardless of how strong the case would otherwise have been, and regardless of who was ultimately at fault.
There are some exceptions. If you were under 18 at the time of the accident, the three years does not usually start running until your eighteenth birthday. If you lack the mental capacity to bring a claim yourself, the clock may not run unless capacity is regained. You can find more detail on how long you have to claim after an accident at work here.
Because working out fault, and any contributory negligence argument, can take time to unpick properly, with witness statements, training records and expert evidence all needing to be gathered, it is worth getting advice well before that deadline rather than close to it.
Frequently asked questions
A few of the questions we are asked most often on this subject, gathered here for a quick answer.
Can I claim compensation if I was partly to blame for an accident at work?
Yes, in many cases. Your compensation will usually be reduced to reflect your share of responsibility rather than refused outright, provided your employer’s negligence contributed in some way too.
What is contributory negligence?
It is the legal principle that lets a court, or an insurer settling out of court, reduce your compensation by a percentage to reflect your own part in causing an accident or worsening your injuries, without defeating your claim entirely.
Can my employer discipline me for an accident that was my fault?
Possibly, if the accident involved genuine misconduct or gross negligence, though they must follow a fair process. An honest mistake made while following normal procedure is unlikely to justify serious disciplinary action, and it does not automatically rule out a compensation claim either.
Do I have to admit fault when I report the accident?
You should be accurate and complete about what happened, including your own actions, rather than trying to hide or downplay your part in it. Being straightforward protects your credibility later on. That is a very different thing from formally accepting legal liability, which is a decision for the insurers and, if necessary, the court.
What if I need money while my claim is being sorted out?
This is separate from your compensation claim. If you are off work because of your injury, you may be entitled to Statutory Sick Pay, currently up to £123.25 a week, or 80% of your average weekly earnings if lower, for up to 28 weeks. Your solicitor can also advise whether an interim payment may be possible once liability is clearer.
How long do I have to bring a claim?
Generally three years from the date of the accident, with exceptions for children and people who lack the mental capacity to claim for themselves, as set out above.
Talk to Mark Reynolds Solicitors
Being told an accident was your fault is not the end of the road, and it should not stop you getting proper advice. We offer a free, no obligation conversation to look at what actually happened, not just what you have been told, and we act on a no win no fee basis so there is no financial risk in finding out where you stand. Read more on the steps involved in making a work accident claim, or contact our team today to talk through what happened. We have offices in Liverpool, Leigh, Runcorn and Warrington, and we are happy to have that conversation whenever you are ready.
Personal injury claims and solicitors: Everything you need to know
Suffering illness or injury due to another party’s negligence can cause extreme pain and distress, financial loss, and even long-term health complications.
If you live in England or Wales, tort law allows you to seek compensation by making a personal injury claim if another party has failed in their duty of care to you.
Personal injury claims cover a broad range of situations, including workplace accidents, road traffic accidents, and slips, trips, and falls.
They don’t just cover physical injuries either; there’s also scope to claim for psychological trauma, long-term occupational illnesses, and subsequent financial losses.
However, the personal injury claims process can be complicated, with claimants required to establish liability and provide evidence of their injuries and any resulting financial losses.
At Mark Reynolds Solicitors, we offer a no-win, no-fee personal injury claims service.
Over time, we’ve helped thousands of people from Liverpool, Leigh, Runcorn, and Warrington to claim personal injury compensation for accidents that weren’t their fault.
This complete guide to personal injury claims explains how the process works, who can make a claim, and how much compensation you may be entitled to.
Contents:
- What is a personal injury claim?
- What types of personal injury can you claim compensation for?
- How long does a personal injury claim take?
- What proof do I need to make a personal injury claim?
- How does the personal injury claims process work? (step-by-step)
- What can you claim compensation for in a personal injury claim?
- How is a personal injury claim valued?
- How much compensation could you receive for a personal injury?
What is a personal injury claim?
Personal injury claims are used to help people claim compensation after they suffer physical or psychological harm due to another party’s negligence or breach of duty of care.
Key requirements for making a personal injury claim are as follows:
- The responsible party owed you a duty of care
- You can prove that the responsible party breached that duty of care
- The breach directly caused your injuries or illness and subsequent losses
A personal injury claim cannot be used to claim compensation if an accident has occurred, but no one is at fault.
What types of personal injury can you claim compensation for?
A personal injury could happen anywhere and to anyone.
We’ve listed some of the most common types of personal injury claims that we handle below:
- Road traffic accidents: Covers claims for road traffic accidents involving cars, motorbikes, bicycles, pedestrians, and all other road users
- Accidents at work: Claims for injuries sustained at work due to unsafe working practices, inadequate training, defective equipment, or an employee otherwise failing to meet their health and safety obligations
- Industrial disease: Claims for illnesses caused by unsafe working conditions, including prolonged exposure to harmful substances like asbestos
- Criminal injury: Claims for people who have been physically or psychologically injured during, or because of, a violent crime
- Abuse claims and sexual abuse claims: Covers claims brought by survivors of physical, sexual, or emotional abuse
- Civil actions against the police: Claims where a person has suffered injury due to police misconduct such as assault or false imprisonment
- MOD compensation claims: Claims against the Ministry of Defence for injuries or illnesses caused by negligence during military service or while working for the MOD
- Armed forces compensation claims: Applications for compensation under the government scheme for serving and former members of the Armed Forces who have been injured or become ill as a result of service
- Product liability claims: Claims for injuries caused by defective, unsafe, or faulty products
- Accidents abroad: Claims for injuries sustained while travelling abroad, including package holidays and hotel accidents
- Housing disrepair: Claims where poor housing conditions like damp, mould, and faulty electrics have caused illness or injury
How long does a personal injury claim take?
How long it will take to receive compensation after making a personal injury claim really depends on the complexity of the case.
On average, most personal injury compensation claims take around 12 to 18 months to settle.
However, simple cases may be resolved within six months if fault is admitted quickly, and complex cases involving very serious injuries could take over two years to settle.
While much of the process is out of your hands, you may be able to speed things up by responding promptly to requests for information, providing supporting evidence as soon as possible, and attending any medical assessments without delay.
What proof do I need to make a personal injury claim?
Providing the right evidence is key to making a successful personal injury claim.
Your personal injury solicitors will explain what evidence you must provide; this will vary depending on the circumstances of the individual claim.
There are two main types of evidence:
| Evidence to prove liability | Evidence of your injuries and financial losses |
| Photographs or videos of the accident scene | Medical records and independent medical reports |
| Photographs of any hazards or defects that contributed to the accident | Photographs of your injuries |
| CCTV or dashcam footage | Notes about calls or conversations with your GP |
| Police or accident reports | Evidence of any care or assistance you’ve needed from family, friends, or professional carers |
| Written account of what happened | A diary recording your symptoms and recovery |
| Witness statements | Receipts and invoices for medical treatment, travel, and other expenses |
| Notes about calls or conversations with insurance companies | Payslips or other evidence of lost earnings |
If the person held responsible denies liability or disputes the value of your claim, then you may be asked to provide further evidence.
Your no-win, no-fee personal injury solicitor can advise you on what additional evidence may help to strengthen your case.
How does the personal injury claims process work? A step-by-step guide
Making a personal injury claim can be a daunting process, particularly if you’re still recovering from an injury.
Our team of personal injury solicitors provide expert legal advice and support during every step of the process.
Here’s a quick step-by-step guide to what to expect when making a personal injury claim.
Step 1: Contact us to receive a free initial consultation
During a free initial consultation, you’ll speak to one of our specialist personal injury solicitors. We’ll ask you some questions about what has happened and advise you on whether you have a case to claim for compensation.
Step 2: Work out who is responsible
Now we need to work out who is at fault for your illness or injury, so we know who to make the claim against. Once we have figured this out, we notify the person, company, or their insurer of your claim.
Step 3: Gather information
We then begin gathering information to build your case by asking you questions about what happened. We will help you collect valuable evidence that proves the injuries you have sustained, the resulting financial losses you have suffered, and the other party’s liability.
Step 4: Medical assessments
You may need to attend a professional medical assessment to establish the extent of your injuries, what treatment is required, the impact the injuries will have on your life, and how long they are likely to affect you for.
Step 5: Interim payments
If you require immediate help covering medical expenses, then we may be able to help arrange interim payments to fund your treatment or rehabilitation. Any interim payments you receive will be deducted from your final personal injury compensation award.
Step 6: Submit your claim
Once we have all the information and evidence required, we will work with you to submit your claim.
Step 7: Negotiations
After calculating how much compensation you deserve, we will enter negotiations with your defendant’s insurer or solicitors. In straightforward cases, settlements are usually agreed quite quickly. However, if liability or the value of the claim is disputed, then it may take a while to negotiate a figure that’s acceptable for everyone.
Step 8: Court (if required)
If an agreement cannot be reached through negotiation, then the claim may need to go to court. If this is the case, a judge will examine the evidence during a court hearing and decide how much compensation to award.
Step 9: Settlement
Once an agreement has been reached, or the court has made a decision, it must be determined how you will receive your payment. Usually, compensation is paid to you in a lump sum once your claim has been completed, but sometimes the court orders it to be paid in instalments if it covers long-term care costs.
What can you claim compensation for in a personal injury claim?
When claiming compensation for a personal injury, general damages compensate you for the pain and suffering caused by the injury.
However, you may also be able to claim for other damages the injury has caused you, such as loss of income and other expenses like medical treatment and ongoing care costs.
Depending on the circumstances of your case, your personal injury settlement could include several different types of compensation, as outlined below:
| Type of compensation | What does it cover? |
| General damages | Compensation for your pain and suffering |
| Loss of earnings | Compensation for income you have lost because your injuries prevented you from working |
| Special damages | Compensation for financial losses and expenses relating to your injury – such as medical treatment, rehabilitation, travel costs, and prescription charges |
| Care and assistance | Reimbursement for the cost of professional care or care provided by friends or family members during your recovery |
| Fatal accident claims | If a family member has died due to another party’s negligence, you may be entitled to compensation for bereavement and other losses |
| Dependency claims | If the person who died provided financial support to dependants, they may be able to claim compensation for loss of financial support |
How is a personal injury claim valued?
Calculating a compensation claim for personal injury is not always straightforward because individual circumstances can vary considerably.
The main principle is that the amount of compensation you can claim is usually proportional to the extent of the injury you have sustained.
Therefore, the more severe your injury and its physical and mental repercussions, the higher the amount of compensation you could receive.
Your personal injury solicitor will assess how much compensation you may be entitled to based on the nature of the injury and how it has impacted you.
When valuing damages, solicitors use the Judicial College Guidelines (JCG), which provide advisory compensation brackets for personal injuries (general damages only) in England and Wales.
The JCG is widely used by solicitors, courts, and insurers as a benchmark when valuing personal injury claims.
The guidelines are updated regularly to account for the changing economy.
They were last updated in April 2026, when the 18th edition of the guidelines was published.
How much compensation could you receive for a personal injury?
Before making a personal injury claim, it’s natural to be curious about how much compensation you could expect to receive.
The table below provides examples of guideline compensation ranges for various personal injuries, taken from the 18th edition of the Judicial College Guidelines published in 2026.
| Type of claim | Type of injury | Severity | Typical compensation range |
| Car accident | Arm fracture | Minor | £8,730 – £25,370 |
| Car accident | Neck injury | Moderate | £10,420 – £50,850 |
| Car accident | PTSD | Moderate | £10,810 – £30,580 |
| Brain and head | Brain injury | Minor | £2,920 – £16,870 |
| Brain and head | Brain damage | Severe | £289,420 – £372,570 |
| Back injury | Back injury | Minor | £3,240 – £16,520 |
| Back injury | Back pain | Severe | £55,660 – £110,990 |
| Workplace accident | Fall from height (back injury) | Moderate-Severe | £16,520 – £212,670 |
| Workplace accident | Occupational dermatitis | Minor-Severe | £2,260 – £25,370 |
| Public liability | Slip on wet floor | Moderate-Severe | £1,620 – £32,480 |
| Public liability | Falls on defective payment | Moderate-Severe | £2,170 – £48,720 |
| Medical negligence | Misdiagnosis of serious illness | – | £21,650 – £270,650 |
| Medical negligence | Birth injuries (to the mother) | Minor-Severe | £8,660 – £108,260+ |
| Industrial disease | Noise-induced hearing loss | Minor-Severe | £9,720 – £119,890 |
| Product liability | Contaminated food | Minor-Severe | £1,200 – £27,070 |
This is only a small sample of the injury categories covered by the JCG, and the figures are intended as a guide rather than a guarantee.
Every personal injury claim is assessed according to its individual circumstances.
These figures only relate to general damages, not special damages like loss of earnings or treatment and care costs – these are calculated separately and then added to your overall compensation award.
Receive a free initial consultation with a personal injury solicitor
If you’ve been involved in an accident and sustained injuries because of someone else’s negligence, you may be entitled to claim compensation.
At Mark Reynolds Solicitors, our no-win, no-fee personal injury claims service aims to make a complicated process as straightforward and stress-free as possible.
We will provide compassionate legal advice and support throughout every step of the process, helping you secure the maximum amount of compensation you are entitled to.
Call us today on 0800 002 9577 for a free initial consultation, or fill in our online contact form, and we will be in touch as soon as possible.
What to do after a road traffic accident in the UK: A step-by-step guide
Being involved in a road traffic accident can be both scary and upsetting.
Whether it’s a minor bump or a more serious collision, you may feel shaken, confused, or unsure what you should do at the scene of the accident.
However, the steps you take after a road traffic accident can make a significant difference to the outcome of your safety, wellbeing, and any future insurance or legal claims.
That’s why it’s so important that you know what steps you should take if you’re ever in a car accident.
Being informed will help you stay calm, protect your legal position, and make sure you have all the information and evidence you need if you decide to make a road traffic accident claim.
Here at Mark Reynolds Solicitors, we have helped countless people from Liverpool, Warrington, Runcorn, and the surrounding areas to successfully claim compensation for all types of road traffic accidents, including whiplash claims and accidents involving bicycles and motorcycles.
In this step-by-step guide, we’ll provide clear and practical advice on what steps you should take both at the scene of the accident and after the event to protect your legal position.
What to do after a car accident UK (step-by-step)
The moments after a road traffic accident can feel chaotic, but it’s important to stay calm.
We’ve created a step-by-step guide that will help you to keep everyone involved safe and gather the information needed to make a road traffic accident claim.
Step 1: Pull over and stop
In the UK, you’re legally required to pull over and stop if you are involved in a collision or any other type of road traffic accident.
Pull over as soon as it is safe to do so, switch off your engine, and turn on your hazard lights to warn other road users of the obstruction.
Step 2: Make sure everyone is safe and seek medical help if needed
Once you have stopped safely, you should check that everyone is ok.
This includes yourself, your passengers, people in other vehicles, pedestrians, cyclists, and any animals involved in the accident.
If anyone is seriously injured, call 999 and ask for an ambulance immediately.
Step 3: Don’t admit or place blame
Being involved in a road traffic accident is stressful and upsetting, and emotions are likely to be running high.
You should avoid discussing who is to blame for the accident and instead keep conversations calm, polite and factual.
Avoid apologising or admitting fault, even if you believe you may have caused the accident.
It’s up to your insurer or solicitor to determine who is liable for the accident, not you.
Step 4: Exchange details with any other drivers involved
To make a road traffic accident claim, you’ll need the insurance details for any other drivers involved in the accident.
You should exchange names, telephone numbers, vehicle registration numbers, and addresses with everyone involved.
Drivers are required by law to share these details, and refusing to do so is a crime.
Step 5: Take photos and make notes
The more evidence you can gather, the stronger your compensation case will be.
Useful evidence that you can gather at the scene of a road traffic accident includes:
- Photos of the accident scene
- Photos of any vehicle damage
- Photos of injuries
- Registration numbers of the vehicles involved
- Notes on weather conditions, road layout, and traffic signals
Step 6: Get witness details
If anyone witnessed the accident, ask to take their names and contact details.
Your insurer or solicitor may want to contact them in the future to request a witness statement if they think it will help your case.
Step 7: Report the accident to the police
Road traffic accidents should be reported to the police if any of the following apply:
- You were unable to exchange details with the other people involved
- Someone was injured
- You suspect the other person may have committed a driving offence
Most police forces in the UK have an online service for reporting road traffic accidents.
Step 8: Notify your insurer and/or contact a solicitor
You should notify your insurer of the accident, even if you don’t plan to make a claim through your insurance.
Check the terms of your policy and then report the incident, providing clear and accurate information about what happened as well as any evidence gathered at the scene of the accident.
Your insurer will then determine liability based on the evidence they receive.
Your insurer can help you to quickly claim compensation for straightforward claims, like minor bumps and simple vehicle repairs.
However, for more complicated cases involving physical injuries, lost earnings, ongoing medical treatment, or other significant financial losses, it is best to seek specialist legal advice.
A road traffic accident solicitor Liverpool can help you to understand your rights and pursue the maximum compensation that you’re entitled to claim.
Contact Mark Reynolds Solicitors to claim compensation for a road traffic accident
At Mark Reynolds Solicitors, we can help you claim compensation for a wide range of different road traffic accident claims, including:
- Whiplash claims
- Back and spinal injuries
- Head and brain injuries
- Broken bones and fractures
- Cycling accidents
- Motorcycle accidents
- Accidents involving pedestrians
- Cases involving uninsured or untraced drivers
- Cases involving children
You may be entitled to make a road traffic accident claim if you have been injured in a road traffic accident that wasn’t your fault.
In some cases, you may still be able to make a claim even if you were partly responsible for the accident.
If you’re not sure whether you have grounds to make a claim, give our team a call on 0800 002 9577 to arrange a free initial consultation during which we will listen to the details of your accident, explain your legal options clearly, and advise you on whether you are eligible to claim compensation.
We operate on a no-win, no-fee basis, meaning you don’t need to pay us anything unless we successfully claim compensation on your behalf. Read our road traffic accident claims testimonials online.
Contact Mark Reynolds Solicitors today to start your no-win, no-fee road traffic accident claim.